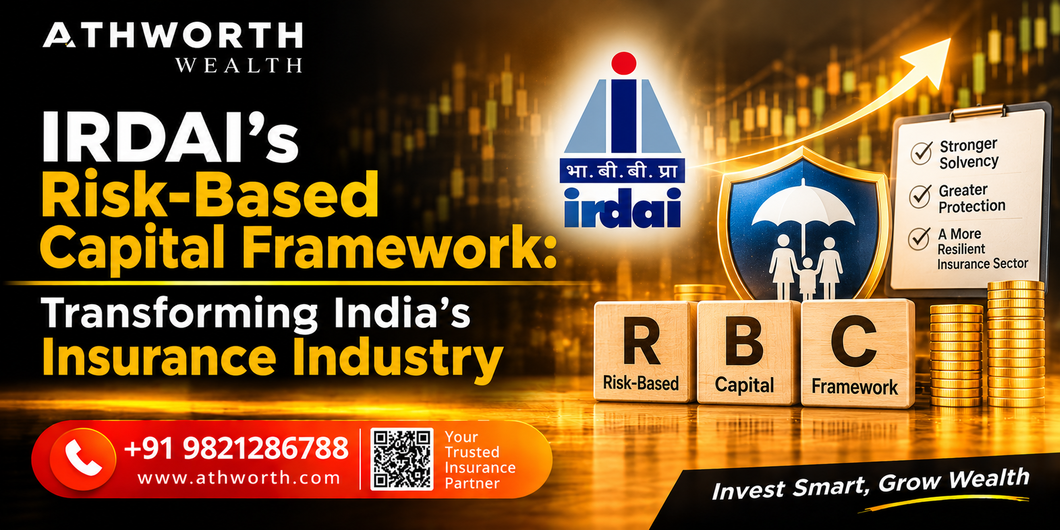
The insurance sector in India will see an essential metamorphosis with the implementation of a Risk-Based Capital (RBC) regime by the Insurance Regulatory and Development Authority of India (IRDAI) in due course of time.
Through RBC, the expected change in capital policy of insurance companies would come into practice, which makes respective insurance companies estimate their capital appropriately, decide on the systematic impact of operational performance in terms of financial stability and assess the risk regarding any particular insurance company. With that approach, there will be a new way for insurance companies to evaluate capital and the results achieved from the stabilization of capital will enable the company to build a more reliable and transparent insurance market.
The change indicates the transformation of the current solvency regime based on a factor system into an entirely new type of risk management process. In this respect, much depends on every detail of the RBC system.
What Is the Risk-Based Capital (RBC) Framework?
RBC (Risk-Based Capital) is a regulatory methodology in which the required amount of capital in an insurance company depends on financial risks related to its operations. The method does not involve the application of standardised capital requirements but takes into consideration the specific risk exposure of the insurance company.
There are certain financial and operational risks that insurance companies are exposed to. These risks include underwriting risks, market volatility, credit defaults, operational risks and catastrophes. All of these types of risks influence the ability of an insurance company to honour the commitments in the future.
Under the RBC system, companies that are exposed to these risks in high amounts will need to hold higher levels of capital. On the other hand, those insurance companies whose portfolios are diversified and whose investments are stable and have strong risk management will benefit from more accurate requirements for their capital.
In the case of an insurance company selling guaranteed-return policies, there will be high interest rate and investment risk. At the same time, a general insurance company that operates in a region prone to catastrophes will have high claims risk.
Moving Beyond India’s Existing Solvency Framework
At present, insurance companies in India practice a solvency-oriented regime. According to current regulatory requirements, all insurance businesses are to maintain a minimum solvency ratio of 150% or above.
In other words, the solvency margin for insurance companies should be equal to at least 1.5 times its required solvency margin. This requirement serves as a comprehensive benchmark for insurers in order to equip themselves with adequate resources for fulfilling their obligations.
At the same time, standardized requirements may fail to capture all the distinctions of different insurers. Within one market, two insurance companies can have different investment portfolio management styles, underwriting policies, customer segments and vulnerability to financial risks.
Applying identical capital requirements can be misleading since it does not take into account all these factors.
The new Risk-Based Capital approach aims to overcome this disadvantage by making capital requirements sensitive to business practices.
This model will enable regulators to see the vulnerable insurance companies.
Why Is IRDAI Aligning the RBC Framework With Ind AS?
One of the key features in the proposed transition process is the IRDAI’s effort to harmonize the Risk Based Capital regime with the Indian Accounting Standards (Ind AS).
IRDAI established two expert working groups on November 10, 2026, to investigate how the proposed approach could be reconciled with the Ind AS based financial reporting. The first working group will deal with life insurance companies, and the second will be dedicated to non-life insurance companies.
The working groups will investigate how the asset, liability and insurance contract valuations under Ind AS will be reflected in the regulatory capital calculations.
It is necessary to make such a transition since the maintenance of two separate accounting and regulatory valuation systems may result in higher administrative costs and complexity of financial reporting.
The suggested convergence will ensure the uniform basis for financial data while preserving the extra requirements for regulatory purposes.
Some of the key topics covered in this process include:
- Contractual Service Margin (CSM): Learning about how expected profits from insurance contracts in the future should be taken into account while doing regulatory capital calculations.
- Expected Credit Loss (ECL): Studying the possibility of credit loss related to financial assets and investments.
- Discounting Methods: Finding suitable ways to calculate the present value of future cash flows.
- Yield Curves: Looking at the interest rate assumptions involved in valuing insurance assets and liabilities.
- Reinsurance Contracts: Considering the treatment of risk transferred to reinsurers in the capital calculations.
- Risk Adjustments: Working out suitable adjustments for the uncertainty involved in insurance liabilities.
This will help in avoiding unnecessary duplication in financial reporting while making sure that the regulatory capital calculations are risk-appropriate.
How Will the New Framework Affect Life Insurance Companies?
The impact of the RBC approach will differ depending on which sector of the insurance business this is applied to. The impact of the RBC approach on life insurance companies is likely to be significant since they are responsible for maintaining financial obligations for periods ranging from several years to several decades.
Such obligations depend on factors like interest rates, mortality rates, investment performance, and behaviour of policyholders.
In a risk-based capital framework, these factors will have a more direct impact on how much capital a company needs to hold.
Products offering guarantees over a long period of time or annuity products may be subject to a thorough review since there are financial obligations in the future for the insurers issuing such products.
Investment-linked products would need thorough evaluation as well since the performance of such investments will depend on changes in the market.
In addition, risks of mortality and longevity could significantly contribute to the capital adequacy needs.
Organisations that have good asset-liability management skills, diverse investment strategies and sound actuarial knowledge will likely be more prepared for the transition.
In essence, the proposed model would push life insurers to be more responsible when developing their products, allocating investments and making plans.
Implications for General and Health Insurance Companies
Changes are also expected for general and health insurers under the proposed framework.
While life insurance policies are long-term and less prone to uncertainty in claims patterns or catastrophic risks, general insurance has relatively shorter policy periods and can be affected by uncertain claims patterns, inflation, and catastrophic events.
General insurance firms will have to look into the issue of underwriting risk. Firms exposed to high risks of loss such as motor insurance, property insurance, and other highly volatile segments will have to keep capital reserves corresponding to the potential losses.
Health insurance firms can be faced with additional issues since health care inflation and other related factors can affect the claims pay-outs. Insurers active in flood-prone, cyclone-prone, or other areas with increased risks of catastrophic events will also have to assess these risks more carefully.
Re-insurance can play an important role for general insurers, allowing them to shift a part of the financial risk to re-insurers. However, it is necessary that the efficiency and reliability of re-insuring transactions be properly considered when assessing capital requirements.
Non-life insurance firms might be encouraged by the proposed framework to adopt better risk management approaches.
Benefits of the RBC Framework for the Insurance Industry
The shift to risk-based financing may assist India’s insurance industry in a number of long-term ways.
- Stronger Financial Stability
Through the linkage of capital requirements to business risk, the framework could aid insurance companies to retain adequate reserves that would be reflective of the risk they face. This would help them manage any unforeseen financial shocks.
- Better Risk Management
Insurance companies may be more active in the identification, quantification and management of various types of risks. It will foster better internal control, more thorough actuarial analysis and decision-making processes.
- Improved Capital Allocation
This approach may allow insurance companies to learn about capital use within particular business units. Consequently, insurers will be able to allocate financial resources more effectively and to focus on profitable business lines.
- Greater Transparency
It may help to enhance the consistency of financial reporting as it aligns capital measurement with accounting data.
- Stronger Policyholder Protection
The most significant one is ensuring that insurance firms have enough financial capabilities to fulfil their responsibilities. Better capital management would create trust in the industry’s capability to meet the demands of claims even in difficult economic environments.
Challenges Insurance Companies May Face During the Transition
However, despite many opportunities offered by the proposed framework, there are some problems that need to be solved when implementing the framework within India’s varied insurance market.
The first one is related to the cost of transition, which will have to be incurred on account of the new technology platform, actuarial modelling system, data management infrastructure and risk assessment expertise.
It is especially problematic for smaller insurers since they have fewer resources, both financial and technical in comparison with the bigger players in the industry.
The other problem is associated with the issue of qualified professionals who will be able to conduct the risk-based capital calculations using actuarial, financial, investment analysis and other required skills.
There is also an issue of reviewing the companies’ own data systems in order to ensure the consistency and correctness of financial statements.
Furthermore, it is vital to find ways to achieve compliance of accounting valuations with the regulatory requirements while maintaining the reliability of financial reporting.
For these reasons, the working groups formed by IRDAI will study the framework and make recommendations based on data and impact analysis.
What Happens Next?
As stated in the ETBFSI report of November 12, 2026, the IRDAI is allowing its two expert working groups a period of one month to come up with their recommendations, accompanied by the exposure draft of the RBC regulations and an approach paper.
The regulator shall then review the recommendations, evaluate their possible impacts and move forward to conduct the stakeholder consultations for the framing of the regulatory framework.
There are several important aspects that need to be decided, such as the final capital calculation formulae, solvency levels and implementation schedule.
It will be very important for the regulators to consult the stakeholders because different insurers follow diverse business models and have different levels of readiness in terms of finance and technology.
A well-thought-out transition schedule will go a long way in helping them become adequately ready in this regard.
The Future of India’s Insurance Industry Under Risk-Based Capital
The introduction of IRDAI’s proposed Risk-Based Capital approach is much more than just a change in the calculation of solvency ratios in insurance companies. It may have an effect on the future development of India’s insurance market by fostering better financial management, risk assessment and capital efficiency.
For the insurance companies, it will imply a need for greater emphasis on risk assessment in respect of various products, investments and activities of their business.
For the policyholders, the ultimate goal is financial stability and trust in insurers’ ability to meet their obligations.
Yet, the successful application of the new approach will be ensured by the right balance between regulatory measures and industry development, so that the capital requirements are strict enough to protect policyholders but not too heavy to make insurance costly and inaccessible.
As IRDAI develops the regulatory framework, there is a good chance that the insurance industry in India can make strides towards a better regulatory system.
Whether or not this can be achieved will depend upon how well insurers, regulators, and others are able to work together to create a more financially sound insurance system.
Frequently Asked Questions (FAQs)
What is risk-based capital in insurance?
Insurance Risk-Based Capital (RBC) refers to the regulation that dictates the minimum capital that should be held by insurance companies, taking into account their size and risk profile in terms of their assets, liabilities, and operations.
What is the regulatory framework for the insurance sector in India?
The Insurance Regulatory and Development Authority of India (IRDAI), a statutory agency created under the IRDA Act of 1999, is principally responsible for regulating the insurance industry in India.
What are the key trends in the insurance industry for 2026?
In 2026, the insurance sector is moving from simple digital testing to full-scale operational execution due to changing capital structures, growing climatic concerns, and artificial intelligence (AI).
What are the 7 pillars of insurance?
Seven key principles of insurance that an investor should be aware of. The seven pillars (also known as basic principles) of insurance are the fundamental principles that apply to every insurance agreement.
- Utmost Good Faith (Uberrimae Fidei)
- Insurable Interest
- Proximate Cause (Causa Proxima)
- Indemnity
- Subrogation
- Contribution
- Loss Minimization
What are the four types of risk in insurance?
The four main categories of risk covered by insurance, which are frequently divided into pure risk classes or the fundamental categories of risk covered by insurance policies, are as follows:
- Pure Risk
- Speculative Risk
- Particular Risk
- Fundamental Risk
What is the biggest threat to the insurance industry?
The largest systemic threat to the insurance sector is climate change, rising losses from natural disasters, social inflation, and cyberattacks.
What are the three main types of insurance?
Health insurance, life insurance, and property & casualty (auto/home) insurance are the three main categories of personal insurance that safeguard your primary assets, your family, and your health.